
Receivables Risk Management: How Growing Companies Can Protect Their Cash
Growing sales should make a CFO feel confident. But there is another side to rapid growth that receives far less attention: receivables risk management becomes increasingly important as more of a company’s revenue is tied up in accounts receivable.
Revenue can increase while financial risk increases with it.
A company may have a stronger sales pipeline, larger customers and more contracts, yet still become more vulnerable if too much working capital is concentrated in unpaid invoices.
That is why receivables risk management needs to grow alongside the sales organization.
Why rapid sales growth can dangerously inflate your credit exposure
Every credit sale creates a future cash inflow.
But until that customer pays, the company is carrying exposure.
If the company has ten customers, the risk may be distributed. If two customers represent 60% of total receivables, the financial consequences of a problem with either one become much larger.
The quality of accounts receivable therefore matters just as much as its total value. Financial analysis commonly uses receivables turnover and DSO to evaluate how quickly receivables are converted into cash.
The danger is that growth can hide the problem.
Sales increase.
Receivables increase.
The balance sheet looks bigger.
But available cash may not increase at the same speed.
Are your sales growing faster than your cash? Find out how much capital is currently exposed in your receivables and talk to ExpoCredit about protecting it.
receivables risk management
Effective receivables risk management requires more than sending payment reminders.
Companies need to understand who owes them money, how much they owe, when they are expected to pay and what would happen if they failed to do so.
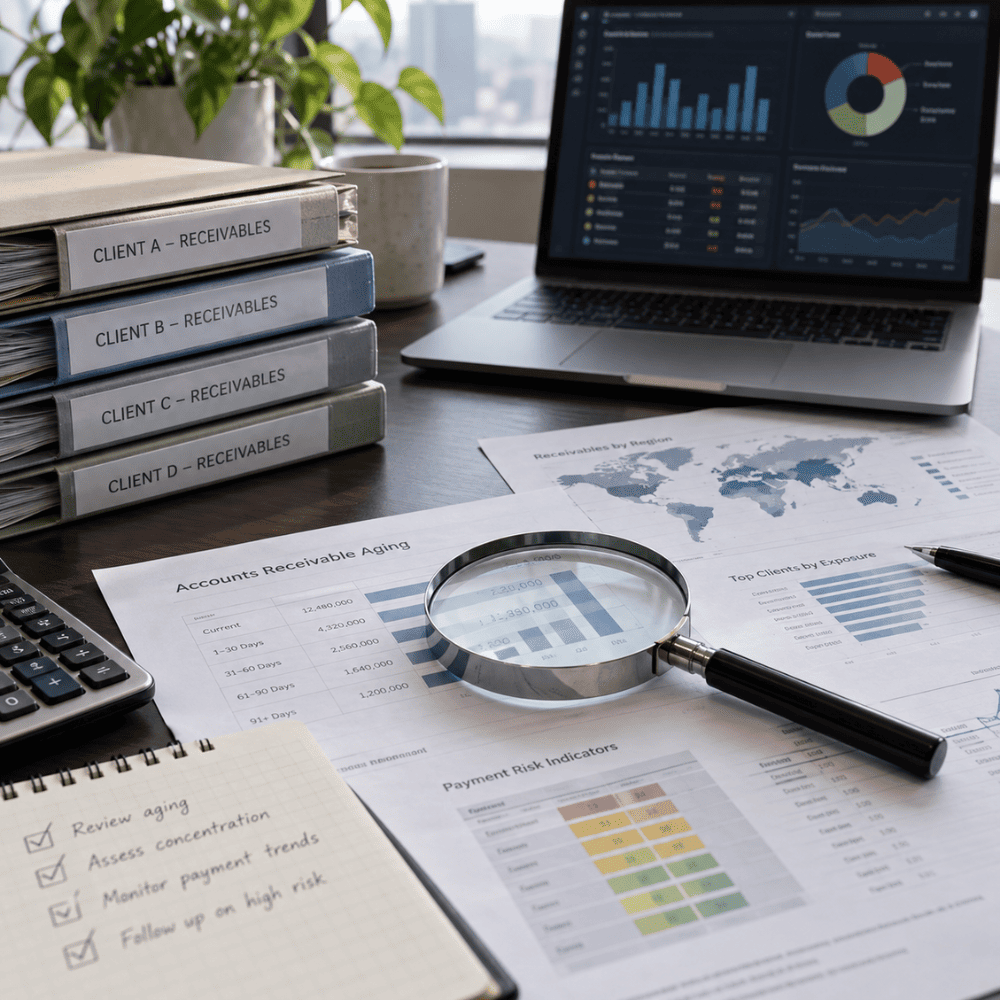
That means monitoring customer concentration, payment behavior, invoice aging and credit quality.
But internal monitoring has one unavoidable limitation: it identifies risk without necessarily removing it.
This is where non-recourse factoring can become a more advanced risk-management tool.
Offloading credit exposure permanently via Expocredit’s non-recourse factoring
With non-recourse factoring, eligible accounts receivable can be sold to ExpoCredit, allowing the company to receive an upfront advance while ExpoCredit assumes the applicable collection and customer default risk under the agreed terms.
This can change the company’s exposure profile.
Instead of carrying the full burden of waiting for the customer to pay, the company obtains liquidity earlier and transfers the applicable credit risk.
ExpoCredit states that its non-recourse model does not require collateral, asset evaluation or financial covenants under its factoring structure.
What would happen to your expansion plans if a major customer suddenly stopped paying? Protect your receivables before credit exposure becomes a growth constraint.
Client testimonial: liquidity that supports sustainable growth
A real ExpoCredit client in the oil and gas industry faced a difficult combination: exponential sales growth, pressure on margins and increasing working-capital requirements.
The company’s CFO explained that despite significant growth, the company needed additional working capital to maintain its operations and competitiveness.
ExpoCredit increased its factoring line to $4 million USD. The company maintained its growth trajectory, strengthened its financial position and preserved the liquidity needed to pursue opportunities in a volatile market.
The experience demonstrates why receivables risk management should not be separated from growth planning.
A company needs to ask not only:
How much can we sell?
but also:
How much credit exposure can we safely carry while we grow?

Core frameworks to safeguard your assets against late payers
The first layer is customer evaluation.
The second is exposure monitoring.
Third is collection discipline.
The fourth is diversification.
And the fifth is risk transfer.
Companies can monitor the quality of their receivables, but they can also use financial structures designed to transfer applicable credit risk.
Factoring can combine liquidity with risk management because the company is not simply accelerating payment; under non-recourse structures, it may also transfer the applicable customer default risk.
Financial peace of mind, predictive budgeting, and secure scaling
When finance teams know that eligible receivables can be converted into working capital, forecasting becomes more predictable.
Instead of waiting for every customer payment to fund the next operating cycle, the company can use factoring strategically to support cash availability.
Is your company increasing sales while simultaneously increasing the amount of credit risk on its balance sheet? Consult an ExpoCredit expert today and explore how to protect your receivables.
Build a robust financial foundation that protects every invoice you issue
Growth should increase opportunity, not vulnerability.
A strong receivables strategy allows companies to pursue larger customers while maintaining control over liquidity and credit exposure.
That requires more than good collections.
It requires visibility, risk monitoring and access to financial tools that can act before a cash shortage becomes a crisis.
ExpoCredit’s non-recourse factoring can serve as one of those tools by providing immediate liquidity and assuming the applicable collection and default risk under the agreed structure.
How much stronger would your growth strategy be if your receivables were generating liquidity without carrying the same level of customer credit exposure? Talk to ExpoCredit and evaluate your portfolio.
Frequently Asked Questions (FAQ) on Receivables Risk and Protection
Receivables risk management is the process of monitoring and mitigating the financial exposure created by customers who owe the company money.
When sales made on credit increase, accounts receivable generally increase as well. This can mean that more of the company’s working capital depends on customers paying according to their terms.
ExpoCredit’s non-recourse factoring allows the company to sell eligible invoices and receive an advance while ExpoCredit assumes the applicable customer collection and default risk under the agreed terms.
ExpoCredit describes non-recourse factoring as a debt-free financing alternative because the company sells its receivables rather than taking a conventional loan.
Yes. By converting receivables into working capital sooner, factoring can help companies fund operations, accept new orders and pursue growth without waiting for every customer to pay.